KEY TAKEAWAYS
- A BIN checker resolves prefix → brand, type, bank and country.
- It never resolves account status — that needs a live check.
- BIN data goes stale as issuers reissue ranges.
- Use it for routing, risk rules and list filtering.
- Store outcomes and identifiers, never PANs, in BIN checking logs.
- Keep the API key server-side and rotate it on any suspicion of exposure.
A BIN checker resolves the leading digits of a card number to the institution that issued it. It is the fastest way to learn the brand, product type and country behind a range — before spending a live check.
What a BIN checker returns
- Brand / network: Visa, Mastercard, American Express, Discover, JCB, UnionPay, Maestro and more.
- Product type: credit or debit (and often prepaid, commercial patterns).
- Issuing bank: the institution behind the prefix.
- Country: the issuer's home market.
Try it now
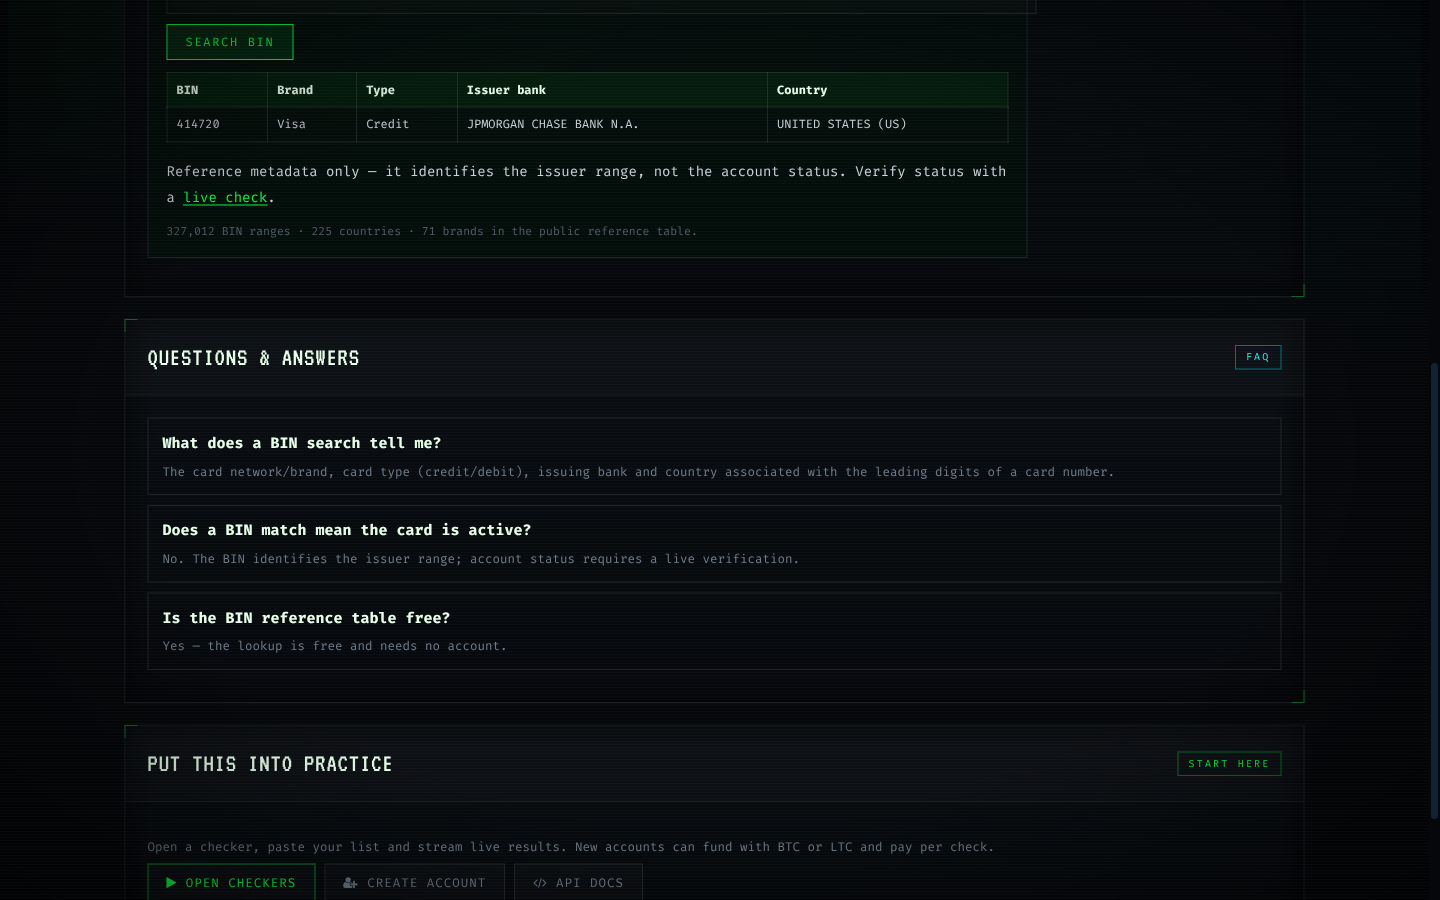
Use the free BIN search (327,000+ ranges) or the client-side BIN lookup for instant brand detection. Both are free and require no account.
What a BIN cannot tell you
A BIN identifies a range, never an account. It cannot say whether a specific card is active, its balance, or whether a charge will approve. Those require live verification. Treating BIN metadata as card status is the most common mistake in payment tooling.
Why BIN data goes stale
Issuers reissue ranges and move portfolios between banks continuously. Refresh reference data regularly, and verify important cards live rather than trusting old metadata.
Where BIN checking fits
- Routing and fee estimation before processing.
- Risk rules comparing card country with customer country.
- Analytics by issuer, product or region.
- Filtering malformed ranges before paid checks.
Continue with BIN vs IIN, IIN lookup and the test card generator for QA fixtures.
The BIN checker resolves leading card digits to issuer reference data: brand, card type, issuing bank and country. It runs against a maintained table of hundreds of thousands of ranges and never claims anything about account status — that is a separate question with a separate tool.
Use it for the jobs reference data does best: routing by issuer, enriching records, validating that a prefix matches the brand you expect, and answering "who issued this" without spending balance.
Issuer reference data for BIN checking
Analysts use BIN distributions to spot shifts in a portfolio long before individual results would show them. The reference table holds hundreds of thousands of issuer ranges, and the tools expose it without any account-status claims. Six digits usually identify the institution; eight add the program or product level on many ranges. Because BIN data is public reference material, it is safe to cache, but it should be re-validated periodically. Remember it the next time BIN checking produces an ambiguous answer.
Reference lookups in BIN checking
BIN metadata complements verification rather than replacing it: reference first, status second. Segmenting by BIN is useful for routing, risk rules and analytics — the places where issuer identity changes behavior. A BIN identifies the issuing institution and network; it says nothing about whether an account is open. The public BIN endpoint serves the same reference data programmatically, read-only and without card data. In BIN checking work, that is the difference between a signal and a guess.
Putting BIN checking to work
Validate checksums and expiry dates before any paid request; the free browser tools exist precisely so malformed rows never reach a provider. Size batches to the provider ceiling. Past that line, extra concurrency converts into timeouts rather than throughput. Start with a pilot of fifty cards. It surfaces format mismatches and routing surprises while the cost of being wrong is still measured in cents. Run one primary gateway with a fallback route. When the primary degrades, re-run only the unclassified remainder on the fallback. That distinction is what keeps BIN checking decisions clean.
Reading BIN checking results honestly
Conflating outcomes is the most expensive habit in this area — an error treated as a dead card discards real inventory, and an unknown treated as live inflates confidence. Errors are free by design: no classification means no charge, so retrying after fixing the cause costs nothing but effort. Dead results are conclusive for the moment and should never be re-checked in the same run; retries on dead cards spend balance for identical answers. A result is only as fresh as its timestamp. High-value decisions should use checks that ran close to the moment of the decision. Holding that line is what makes BIN checking reliable over time.
Using BIN checking on the right side of the line
Where a check is used inside a payment flow, it complements authorization rather than replacing it. Verification is a signal, not a guarantee: a live result does not promise that a later charge will be approved. High-value decisions deserve fresh checks; stale results drift as accounts change. Holding that line is what makes BIN checking reliable over time.
The toolkit around BIN checking
The Luhn validator and expiry checker catch format problems before any paid request leaves the browser. The check-digit calculator shows the Luhn math step by step, useful when building or debugging number generation. Every browser tool runs client-side: input never leaves the page, which keeps format validation free and private. Holding that line is what makes BIN checking reliable over time.
Scaling BIN checking without surprises
Document the route, the batch policy and the retry rules next to each production run; six months later that note is the diagnosis. Keep the API key server-side and regenerable; a leaked key is a billing incident as much as a security one. Reconcile spend monthly against classified results; the difference between the two numbers is where retries hide. Treat provider outages as routing problems: switch routes, recover the unclassified remainder, keep the answers you already paid for. Keep it in mind whenever BIN checking results are reviewed.
Pitfalls that cost money in BIN checking
Skipping format validation before BIN checking turns simple input mistakes into provider rejects that look like card problems. Mixing test numbers into production BIN checking lists creates results that mean nothing. Scheduling BIN checking after the decision it informs removes most of its value.
- Comparing BIN checking routes on list price instead of classified rate hides the real economics.
- Retrying a dead card during BIN checking spends balance for an answer that will not change within the run.
- Using BIN reference data as account status in BIN checking confuses two different questions and produces confident, wrong decisions.
- Ignoring cost per classified card hides the real price of a cheap BIN checking route with a high failure rate.
Limits and responsible use of BIN checking
Verification is at its best when it is boring: a routine status step inside an existing, authorised process. Where a check is used inside a payment flow, it complements authorization rather than replacing it. High-value decisions deserve fresh checks; stale results drift as accounts change. That distinction is what keeps BIN checking decisions clean.
Validation helpers for BIN checking
Pair the generator with the Luhn validator when building test fixtures; checksum-valid numbers exercise real validation paths. The CSV cleaner normalises separators and removes duplicates, which is the cheapest way to protect a large run. The test card generator produces checksum-valid numbers for development, and they are never chargeable by design. It is a small rule that changes how BIN checking behaves at scale.